 how-to
How to Qualify for FHA Loans in Miami: Requirements Guide
Table of Contents
- FHA Loan Basics for Miami Homebuyers
- FHA Loan Credit Score Requirements
- FHA Loan Down Payment Requirements and Costs Beyond the Down Payment
- Income, Debt-to-Income Ratio, and Documentation
- Miami-Dade FHA Loan Limits and Eligible Properties
- Miami First-Time Homebuyer Programs and Down Payment Assistance
- FHA vs. Conventional Loans for First-Time Buyers
- Start Your FHA Pre-Qualification With Jr Mortgage
- Frequently Asked Questions
Last Updated: November 1, 2026
FHA Loan Basics for Miami Homebuyers
Learning how to qualify for FHA loans in Miami is easier than many first-time buyers expect. The core rules are the same everywhere. For the full list of requirements that apply to first-time buyers, see FHA loan requirements for first-time buyers. An FHA loan is a mortgage insured by the Federal Housing Administration, which is part of the U.S. Department of Housing and Urban Development (HUD). That insurance lets lenders accept lower credit scores and smaller down payments than most conventional loans allow.
Here is what qualifying usually involves:
- A credit score and credit history that meet the lender's minimum
- A down payment, which for many qualifying borrowers is 3.5% of the purchase price
- Steady, verifiable income and employment
- A debt-to-income (DTI) ratio within FHA limits
- A home that meets FHA property standards
Think of these as the main checkpoints. Each one is covered below.
FHA Loan Credit Score Requirements
Credit score is usually the first thing lenders check when you research how to qualify for FHA loans in Miami. HUD sets the baseline, but each lender adds its own rules, called overlays.
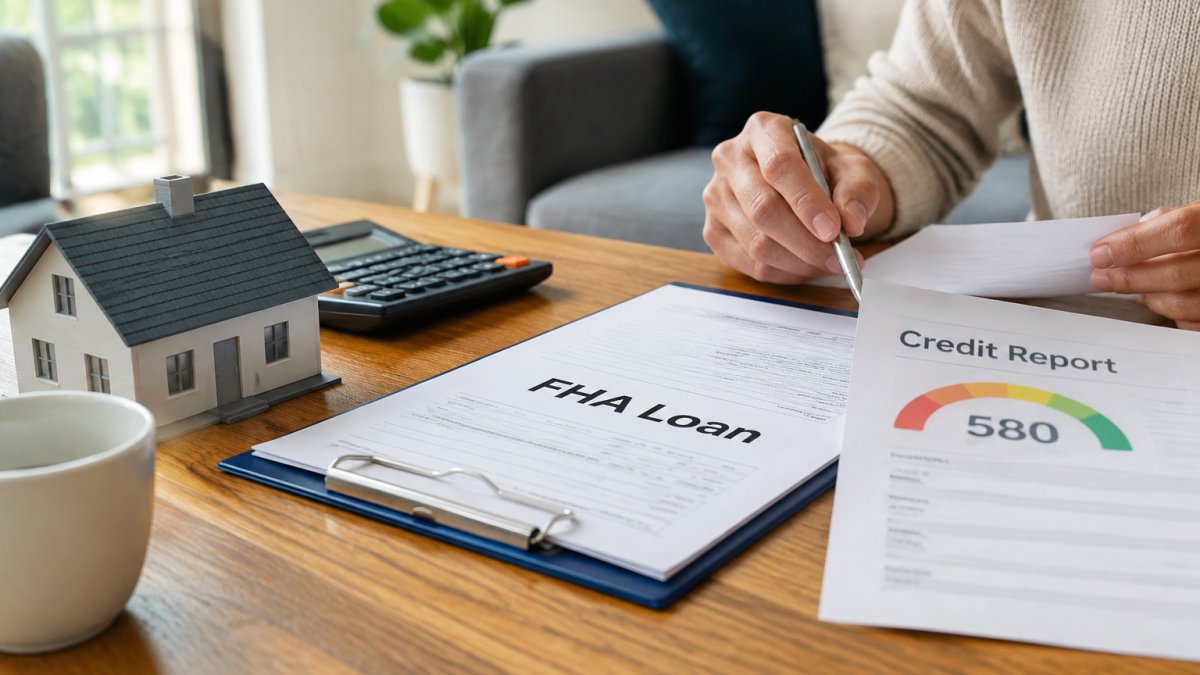
- A 580 or higher score generally qualifies for the 3.5% down payment option
- A score between 500 and 579 may qualify with a 10% down payment
- Many lenders set a higher floor than HUD requires, so check before you apply
A low score does not end the conversation. Paying down revolving balances and correcting report errors can move your score in a few months.
The article sets out the credit score ranges and down payment options that lenders check first.
| Credit score | Down payment option | Note |
|---|---|---|
| 580 or higher | 3.5% | Generally qualifies for the standard option |
| 500 to 579 | 10% | May qualify with the larger down payment |
| Below 500 | Not stated | Article does not give a qualifying path |
| Lender minimums | Varies | Many lenders set a higher floor than HUD |
FHA Loan Down Payment Requirements and Costs Beyond the Down Payment
The down payment is the cash you bring to closing. For most qualifying borrowers it is 3.5% of the purchase price. On a $400,000 home, that is $14,000. To see how much cash to bring to closing, read the detailed FHA down payment breakdown.
Plan for costs beyond the down payment too:
- Upfront mortgage insurance premium (UFMIP), which can be financed into the loan
- Annual mortgage insurance premiums, paid monthly
- Closing costs such as appraisal, title, and lender fees
- Prepaid items like homeowners insurance and property taxes
Ask for a Loan Estimate early. It lists these costs in one place so there are no surprises at closing.
Income, Debt-to-Income Ratio, and Documentation
Lenders need to see that your income is stable and that you can afford the payment. Most FHA borrowers document income with:
- Two years of W-2s or tax returns
- Recent pay stubs covering the last 30 days
- Employment history covering the last two years
Self-employed buyers usually provide two years of personal and business tax returns. For the specific income and documentation rules that apply to you, see FHA loan requirements for self-employed buyers.
Your debt-to-income ratio compares your monthly debts to your gross monthly income.
Miami-Dade FHA Loan Limits and Eligible Properties
FHA sets a maximum loan amount for each county, and HUD updates the figures every year. FHA sets a maximum loan amount for each county, and the applicable limit can differ by county.
Because the limit resets annually, always confirm the number in effect on your application date. You can check the current FHA mortgage limit for your county through HUD's official lookup. HUD FHA Mortgage Limits lookup
How the limit caps your purchase budget
The FHA loan limit is a cap on the loan amount, not on the purchase price.
- A larger down payment raises your maximum price; a smaller one lowers it.
Property types FHA will finance in Miami-Dade
FHA can finance:
- Single-family detached homes
- Two-to-four unit properties, provided you live in one unit as your primary residence
- FHA-approved condominiums
- Townhomes and certain planned-unit developments that meet project standards
Condo project approval, check this first in Miami
A condo unit is generally only eligible if the project is on FHA's approved list or meets the project standards HUD applies. Before you fall in love with a unit, ask the listing agent for the project's FHA status and verify it on HUD's condo lookup. HUD FHA Condo Approval lookup
Appraisal and property-condition standards
FHA requires an FHA-approved appraiser and applies minimum property standards: the home must be safe, sound, and secure. Common property issues that can come up in FHA appraisals include roof condition, peeling paint on older homes, and evidence of water intrusion. The appraiser may require repairs before closing, and those repairs are typically the seller's responsibility to negotiate. Budget time for a possible repair negotiation, it is a normal part of an FHA purchase, not a red flag.
Flood and insurance considerations
FHA requires flood insurance when the property is in a Special Flood Hazard Area. Flood insurance premiums vary widely by elevation and zone, and they are part of your monthly housing cost for DTI purposes. Ask for a flood zone determination and an insurance quote early, a premium that looks small on paper can move your debt-to-income ratio enough to change your qualification.
What to verify before you make an offer
- Current FHA loan limit for the property's county and unit count.
- Condo project FHA approval status (if applicable).
- Flood zone and estimated flood insurance premium.
- Any obvious property-condition items likely to appear in the FHA appraisal.
Checking these four items before you write an offer is the difference between a smooth FHA closing and a contract that stalls on appraisal or insurance.
Miami First-Time Homebuyer Programs and Down Payment Assistance
Most FHA guides stop at "3.5% down" and never explain how buyers actually cover that cash. In Miami-Dade, several layers of assistance can reduce the upfront burden, but each has its own eligibility rules, and the rules change. The practical approach is to identify the programs you may qualify for during pre-qualification, not after you find a house.
The main sources of down payment help
Statewide programs. Florida state agencies administer first-time homebuyer assistance programs in some cases, which may be available to eligible buyers. These programs typically have income limits, purchase price limits, and a homebuyer education requirement, and assistance is often structured as a second lien that may be forgivable or repayable depending on the program. Ask your loan officer which Florida Housing program is currently open and whether it can be combined with an FHA first mortgage. Florida Housing Finance Corporation homebuyer programs
County and city programs. Some counties and cities offer their own down payment assistance programs, and availability depends on funding cycles.
Employer and nonprofit assistance. Some employers and nonprofit housing counseling agencies offer grants or matched savings.
How assistance interacts with your FHA loan
Down payment assistance usually comes as a second mortgage, a grant, or a deferred loan. Lenders must count the payments on any second lien in your debt-to-income ratio unless the program documents specify otherwise. That means assistance can help you with cash at closing while still affecting how much you can borrow on the first mortgage. Ask your loan officer to model both scenarios: with and without the assistance.
Also confirm what the assistance can pay for. Some programs cover only the down payment, some cover closing costs, and some cover both. FHA allows the 3.5% minimum down payment to be met with eligible gift funds and certain assistance programs, but the lender must document the source carefully.
Eligibility factors to expect
Assistance programs generally look at:
- Household income against Area Median Income limits (which vary by household size)
- Purchase price against program limits
- First-time homebuyer status (generally no ownership in the past three years, with some exceptions)
- Completion of a homebuyer education course
- Primary residence requirement
- Available program funds at the time you apply
A realistic sequence
- Complete a HUD-approved homebuyer education course early, it is required by many programs and does not expire quickly.
- Get pre-qualified for the FHA first mortgage so you know your price range.
- Ask your loan officer and a housing counselor which assistance programs are currently funded and compatible with your FHA loan.
- Submit assistance applications in parallel with your home search, funding can run out, and approval timelines vary.
- Confirm with your lender how any second lien affects your debt-to-income ratio before you make an offer.
FHA vs. Conventional Loans for First-Time Buyers
FHA loans accept lower credit scores and smaller down payments. Conventional loans often have lower long-term mortgage insurance costs for borrowers with strong credit, and their cancellation rules can be more favorable. The right choice depends on your credit, savings, and how long you plan to stay in the home. Before you commit, learn how to pick a lender in how to choose a mortgage lender for your first home.
Start Your FHA Pre-Qualification With Jr Mortgage
Ready to see where you stand? Contact Jr Mortgage to review your credit, income, and down payment options, and apply for a loan now.
Frequently Asked Questions
What credit score do you need to qualify for an FHA loan in Miami?
FHA loans are insured by the Federal Housing Administration and are generally available to borrowers with a FICO score of 580 or higher when making the minimum 3.5% down payment. Borrowers with scores between 500 and 579 may still qualify but typically need a 10% down payment. Individual lenders often set higher minimums through their own overlays, so it is worth confirming the threshold before you apply. Jr Mortgage can review your credit profile and explain which options fit your situation.
How much down payment do you need for an FHA loan?
The minimum down payment for an FHA purchase loan is 3.5% of the purchase price when your credit score is 580 or higher. Borrowers between 500 and 579 need at least 10%. Gift funds from family members, employers, or qualifying nonprofits can often cover the down payment, and some Miami-Dade programs offer down payment assistance that can be combined with an FHA loan. Your total cash needed at closing also includes closing costs and prepaid items, so plan for those separately.
Can first-time homebuyers qualify for an FHA loan in Miami?
Yes. FHA loans are one of the most common options for first-time buyers because of their lower credit score and down payment thresholds. You do not have to be a first-time buyer to use FHA financing, but many buyers in Miami-Dade use it for their first purchase. To qualify you will generally need steady, verifiable income, a debt-to-income ratio within guideline limits, and a property that meets FHA appraisal standards. A loan officer can walk you through the full checklist before you make an offer.
What documents do you need to apply for an FHA loan?
Most lenders will ask for recent pay stubs covering the last 30 days, W-2 forms from the past two years, federal tax returns, bank and asset statements, government-issued photo identification, and your Social Security number. Self-employed borrowers usually provide two years of personal and business tax returns and a profit and loss statement. Having these ready before you apply can shorten underwriting. Jr Mortgage can provide a personalized document checklist based on your employment and income type.